Limit unsafe exposure
Stay off the roof and away from electrical hazards or sagging ceilings. Discuss temporary protection if an opening is admitting water.
Gladstone, MO
The roof’s repair needs and the insurer’s coverage decision are separate. Understanding the deductible and payment terms makes the roofing budget easier to follow.
Insurance generally responds to covered causes under the policy, not simply to the roof becoming old. A roof assessment describes current condition and the work needed. The insurer evaluates the claim under the policy’s cause, exclusions and payment terms.
These terms affect what the owner pays even when roofing work is covered.
| Term | What it means |
|---|---|
| Deductible | The part of covered loss the policyholder is responsible for under the policy. It can be a fixed amount or a percentage. |
| Actual cash value | A payment basis that accounts for depreciation under the policy. |
| Replacement cost | A payment basis tied to repair or replacement under stated conditions, often with depreciation initially withheld. |
| Recoverable depreciation | A withheld amount that is payable only if the policy’s requirements are met. |
| Supplement | A request for the insurer to review additional documented scope or damage; it is not automatic approval. |
Keep the roofing work and the claim process connected without treating them as the same decision.
Stay off the roof and away from electrical hazards or sagging ceilings. Discuss temporary protection if an opening is admitting water.
Report suspected covered damage promptly through the policy’s claim process. Policy notice requirements and the insurer’s instructions control the claim.
The inspection and any newly exposed conditions help define the work. Additional claimed damage still needs review by the insurer.
A deductible is part of the claim’s financial arrangement, not a roofing discount.
Missouri law prohibits a residential roofing contractor from advertising or promising to pay or rebate an insurance deductible as an inducement. The project budget needs to account for the actual deductible.
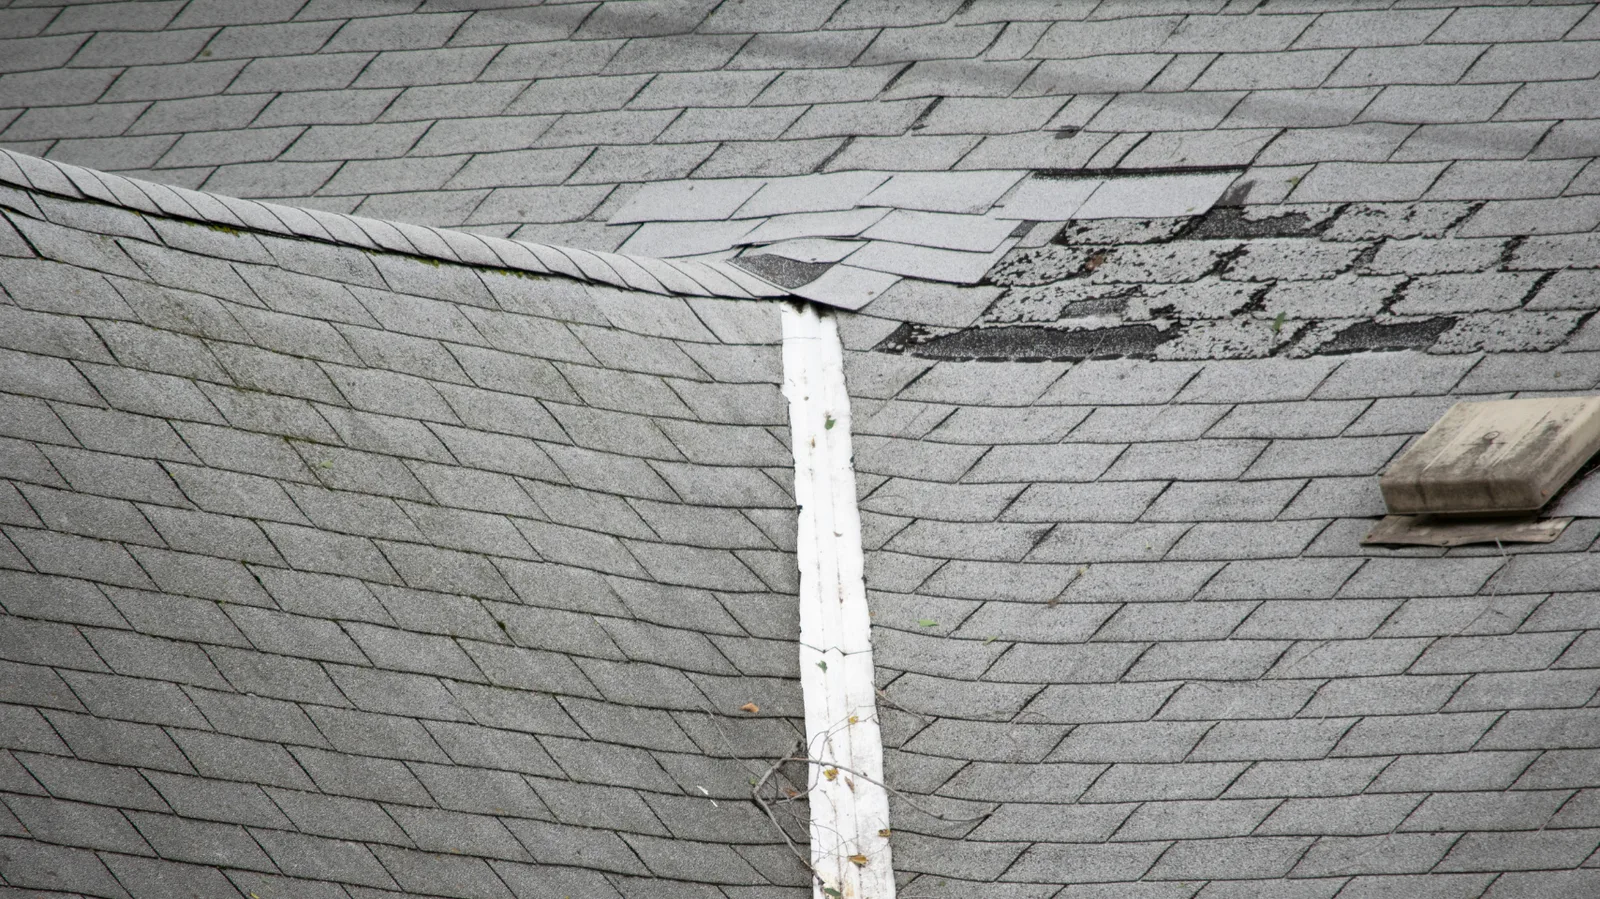
Wear, exclusions, prior conditions and policy wording affect payment. A replacement recommendation does not itself establish an insured loss.
Materials, hidden decking damage and roof details determine the physical repair even when claim payment is being reviewed.
Age alone does not establish a covered loss. A suspected covered event, the roof findings and the actual policy guide the conversation. A free roof inspection can help establish the condition, while the insurer decides coverage.
Not necessarily. Deductibles, depreciation, covered scope and policy limits affect payment. Work outside the covered scope remains a separate budget question.
The roofing information here is general guidance. The insurer handles coverage under the policy; claim representation and legal advice are separate professional services.
Gladstone Roof Pros
Tell us the concern and the property location. Start with the roof’s condition and the repair it needs.
(816) 439-0392